For real estate agents and mortgage lenders, finalizing a new construction transaction is an exciting milestone. The property is pristine, the systems are brand new, and your clients are eager to receive their keys.
However, the path to settling a newly built home contains unique legal compliance layers that do not exist in standard residential resales. The most critical risk factor involves mechanics liens, which are legal claims filed by contractors, subcontractors, or material suppliers who have not been fully paid for their work.
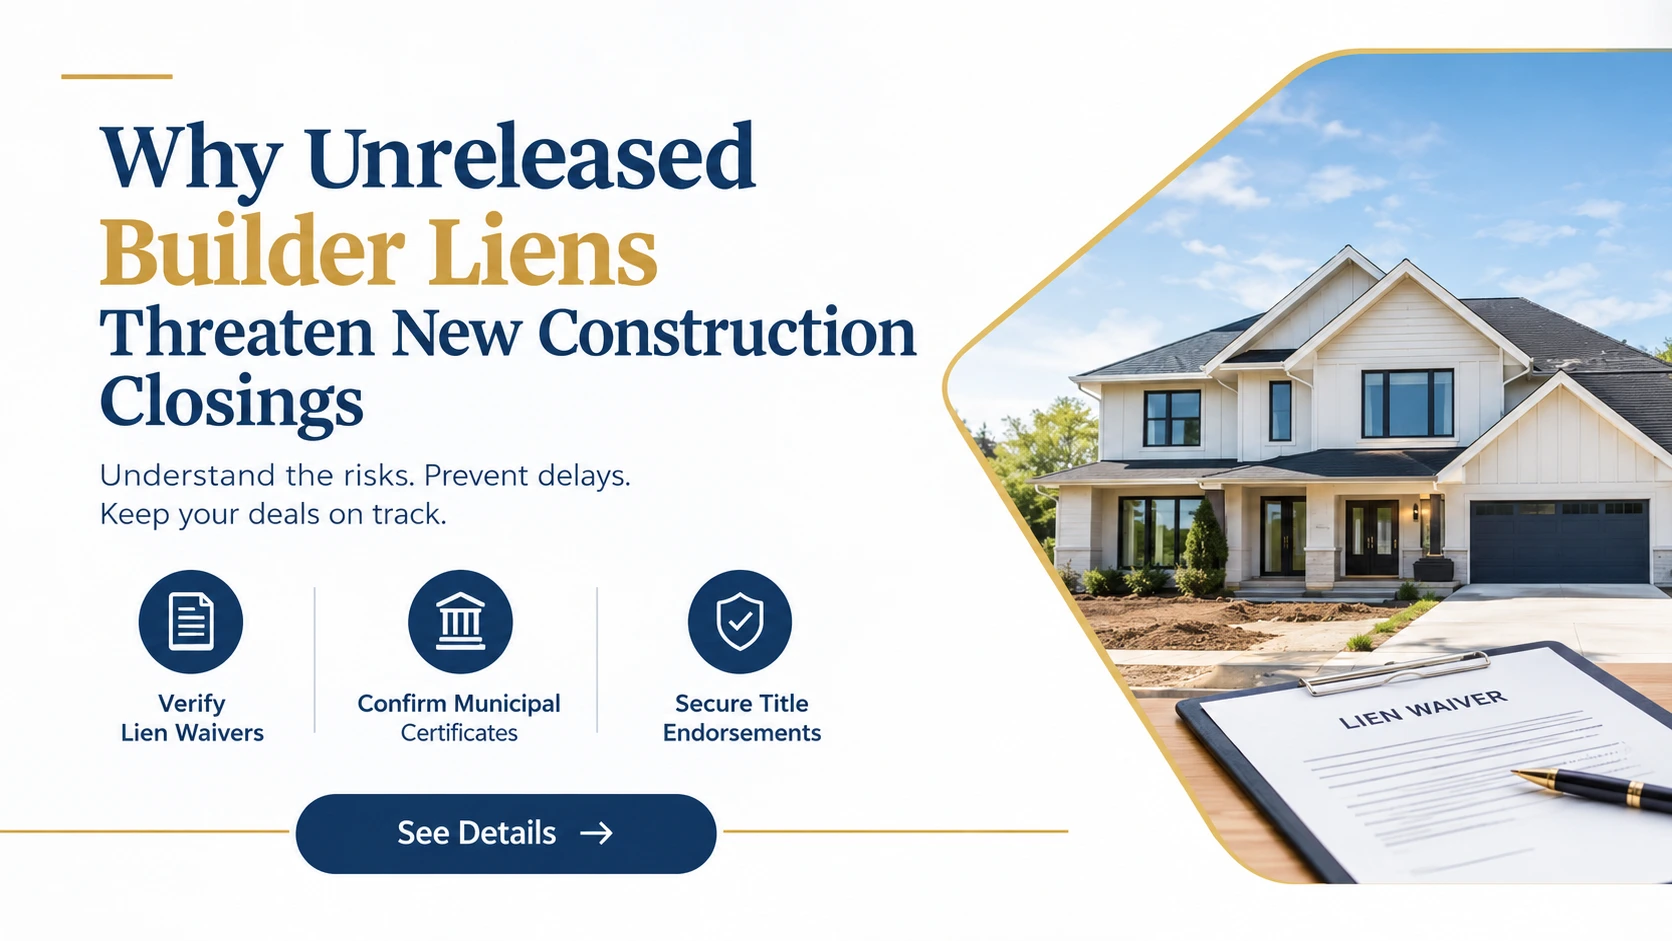
If these claims are not identified and cleared before settlement day, the lender will withhold the clear-to-close approval. This delay can cause interest rate locks to expire and stall the entire transaction. By understanding how these hidden encumbrances occur, real estate professionals can partner with a proactive title team to protect their files. Here is a breakdown of why unreleased builder liens occur and the specific steps required to prevent them.
- The Gap Timeline Between Construction and Public Recording
A primary cause of new construction closing delays is the chronological delay in public record logging. In many local jurisdictions, contractors and suppliers possess an extended legal window, frequently up to ninety days after completing their work, to record a lien against a property for unpaid services. This means a title search conducted right before closing might show a clear record, even if a subcontractor is planning to file an unpaid claim the following week.
The Solution:
Title teams must look beyond standard historical land records when managing new construction transactions. Proactive settlement firms secure formal, signed mechanics lien waivers from the general builder and all primary subcontractors before closing. These legal documents verify that all parties have received full payment for their labor and materials, completely eliminating the possibility of a future claim against the home.
- Discrepancies in Outstanding Subcontractor Invoices
The financial architecture of building a home is highly complex, involving multiple tiers of vendors, from foundation specialists to final interior painters. A frequent bottleneck occurs when a dispute arises between the main homebuilder and a specific vendor regarding the quality of work or final invoice totals. If the builder holds back payment during negotiations, the subcontractor can file a claim directly against the property deed, halting the buyer’s loan funding instantly.
The Solution:
Establishing an open channel of communication with the builder’s financial team early in the transaction prevents administrative friction. Title processors actively request comprehensive builder affidavits at intake. These legal declarations require the builder to list every supplier involved in the project, allowing the settlement firm to confirm that all balances are zero well before closing documents are prepared.
- Missing Municipal Certificates and Final Title Endorsements
Lenders require absolute verification that a new home is legally complete and structurally sound before releasing loan funds. A closing bottleneck occurs when a transaction approaches settlement without a final Certificate of Occupancy from the local county municipality, or without the specific mechanics lien title insurance endorsements required by the bank’s underwriting department.
The Solution:
Clear communication and direct accountability prevent these municipal documentation gaps from delaying your transaction. Both organizations should assign a dedicated point of contact to monitor building inspections and county filings from day one. Direct coordination between the title team, the builder, and the mortgage processor ensures that final municipal approvals and specialized title insurance protections are secured early in the transaction.
Partnering for Seamless Closings
A successful closing begins long before closing day. When real estate agents, lenders, and title professionals work together, navigating new construction guidelines becomes a routine administrative step rather than a last-minute scramble. Our experienced team remains dedicated to protecting your client relationships and keeping your real estate transactions on schedule.
When your transaction has a dedicated processor from contract to closing, communication is clear, accountability is built in, and nothing falls through the cracks. Whether your transaction brings you to our offices in Tysons, VA; Fairfax, VA; Richmond, VA; Rockville, MD; West Palm Beach, FL; or Washington, DC, each agent and lender receives a dedicated processor for a truly personalized title experience.
Behind every smooth closing is a dedicated team managing details with precision. With over 1,200 successful closings in under four years and a 92.5 percent year-over-year client retention rate, AtoZ Title & Settlement has earned the trust of agents and lenders across Virginia, Maryland, DC, and Florida. We know what it takes to protect transactions.
AtoZ Title & Settlement Team
Ready to partner with a team that prevents delays before they happen? Reach out to AtoZ Title & Settlement at (888) 615-2869 or visit atoztitle.com. We serve real estate professionals across Virginia, Maryland, Washington DC, and Florida, and we are committed to keeping your transactions on track and your clients confident from contract to closing.